
Market Commentary
- Structural tailwinds continued to propel the secondaries market in H1 2026, as persistent liquidity constraints, growing GP adoption of continuation vehicles across asset classes, and an expanding buyer universe combined to produce strong first-half volume and set the stage for another year well over $200 billion in transaction volume.
- LP liquidity needs remain a central source of secondary market activity, with annual distribution yields holding near 10% in H1 2026, well below the long-term historical average of approximately 25%.
- Total dedicated secondaries capital fell to $290 billion from $327 billion at the end of H2 2025, while total available capital fell to $328 billion from $477 billion at the end of 2025, signaling a contraction in dry powder as capital deployment accelerates.
- Deployment continues to broaden across non-U.S. geographies, particularly in Europe, where GP-led volume reached approximately $15 billion, or 24% of the global market, and is projected to approach $35 billion for full-year 2026.
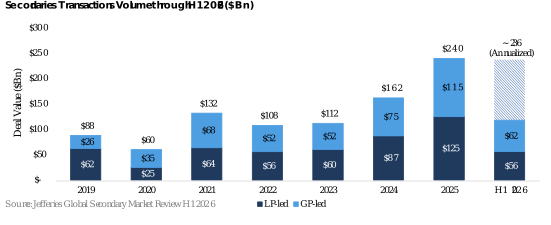
The secondary market has become a permanent capital channel, with H1 2026 volume reaching $118 billion (+15% YoY).
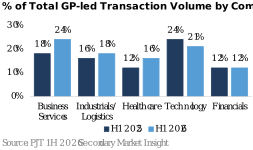
GP’s rotated toward hard asset sectors with low obsolescence in H1 2026 like Business Services, Healthcare, and Industrials, while technology interest wavered amid AI and valuation concerns.
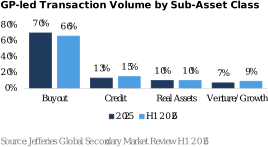
GP-led transactions for buyout funds fell to 66% of the secondaries market in H1 2026, down from 70% in 2025, as continuation vehicle activity for credit and AI-linked venture and growth investments outpaced the growth of the overall secondaries market.
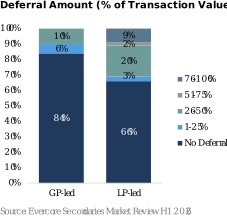
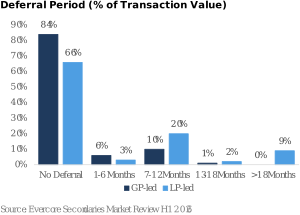
Deferred consideration is now a standard structuring tool, with about one-third of LP-led deals including deferrals; LP-led buyers use them to support returns, and most settle within 12 months, reflecting pricing and financing calibration rather than long-term risk transfer.
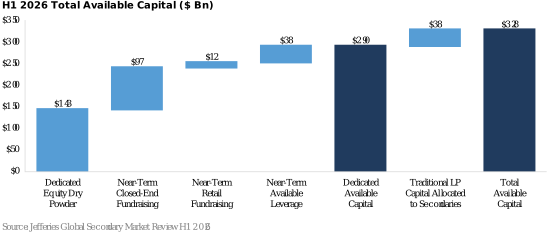
Dedicated available capital declined to $290 billion from $327 billion at year-end 2025 (1.2x LTM overhang). Including traditional allocations, evergreen vehicles, and leverage, total capital reaches ~$328 billion, indicating the market remains well-capitalized despite elevated deployment activity.
Stay Up To Date with Ropes & Gray
Ropes & Gray attorneys provide timely analysis on legal developments, court decisions and changes in legislation and regulations.
Stay in the loop with all things Ropes & Gray, and find out more about our people, culture, initiatives and everything that’s happening.
We regularly notify our clients and contacts of significant legal developments, news, webinars and teleconferences that affect their industries.