
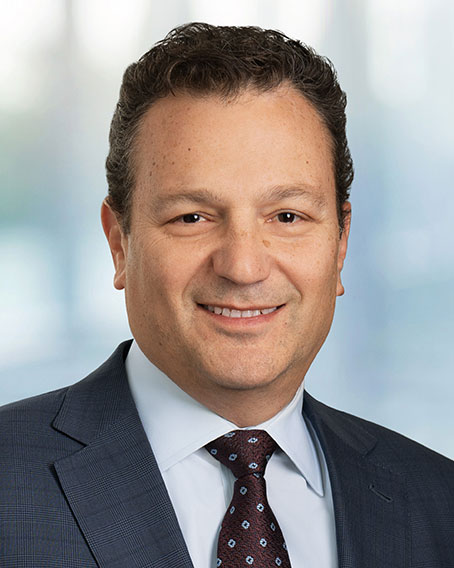
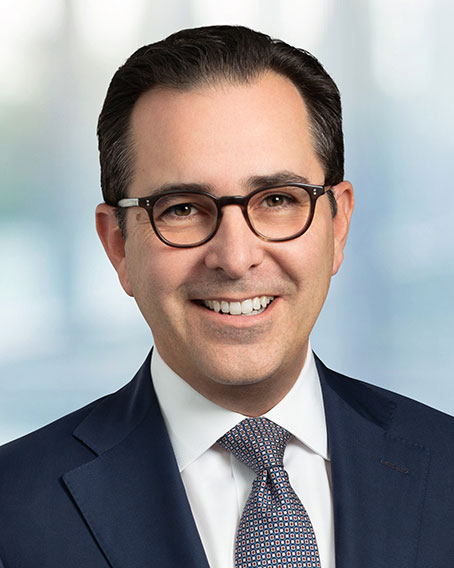
On this Ropes & Gray podcast, Craig Marcus, co-head of the firm’s capital markets practice, and Marc Migliazzo, counsel in the asset management group, discuss the SEC’s new exemptive order impacting GP-led secondary transactions. The episode explores the shift from a 20-business day election period to a potential 10-business day standard, the requirements for qualifying tender offers, and the practical challenges for sponsors and LPs. Marc and Craig examine how the new order may affect transaction timelines, investor decision-making, and market practices, providing valuable insights for asset managers, private fund sponsors, and institutional investors navigating these complex deals.
Transcript:
Marc Migliazzo: Welcome to this Ropes & Gray podcast. My name is Marc Migliazzo. I’m a member of Ropes & Gray’s asset management practice, based in Boston. I’m pleased to be joined today by Craig Marcus, who is co-head of the capital markets practice at Ropes & Gray, also based in Boston. Craig, thanks for spending some time to talk to us about the new exemptive order that the SEC has issued. So, there’s been a 20-day business minimum that has featured as part of the election process for GP-led secondary transactions. Why is that?
Craig Marcus: So, most GPs structured their continuation fund rollover or sale elections to comply with the U.S. tender offer rules, which, as a general matter, require the election period to remain open for 20 business days. This minimum period of time has effectively become the market standard for these GP-led secondary transactions. Until this exemptive order, that was the way people complied with the tender offer rules.
Marc Migliazzo: In April of this year, the SEC issued a new exemptive order that significantly reduces the time that certain tenders for equity securities must remain open. Tell us a bit about that.
Craig Marcus: This is an exemptive order, so it doesn’t change any rules, but it changes the way that the SEC staff will interpret the rules. And it provides an opportunity to run a tender-offer process where the tender offer only has to be open for 10 business days instead of the traditional 20. And this applies both under the Rule 13e-4 issuer tender rules and the Rule 14e-1 third-party tender rules. To constitute a qualifying tender offer, which is what gets you the benefit of the 10-business day period, the tender offer needs to meet a few criteria, which include, most importantly, for these purposes, the tender being for a cash-only fixed-price offer, and that has to be made by the issuer or one of its subs. And so, this basically means that sponsors structuring continuation fund elections can—if they can make the tender offer a qualifying tender offer—shorten up the election period if they offer to LPs.
Marc Migliazzo: Got it. So, do you think this means election periods and GP-led transactions are likely going to immediately shift to a 10-business day standard?
Craig Marcus: So, my guess is not likely. Most private funds are not Exchange Act reporting companies, and as a result, most of these GP-led secondary transactions can fall within the exemptive order’s provisions for non-reporting companies. But the significant practical limitation is the one I had mentioned earlier, which is, it has to be a cash offer at a fixed price. No formula pricing. No securities-based consideration. No contingent value rights. Nothing other than X dollars for the interest. And continuation fund elections, as you know, typically are not all-cash, fixed-price the way they’re currently structured. They give LPs the choice between rolling into the continuation vehicle or cashing out, and it’s typically based on a formula that takes into account a reference price and then increases or decreases for distributions and contributions, and an adjustment for transaction expenses. And so, while you could imagine seeing GPs restructuring their transactions to satisfy the fixed-price requirement, it would require them changing a little bit the way their transactions are marketed and the way that they’re constructed. And so, whether that would be worthwhile to get the benefit of the 10 business days versus sticking with a method that has worked for them remains to be seen.
Marc Migliazzo: It does sound like fairly meaningful deviation from the way the continuation vehicle transactions are typically structured these days.
Craig Marcus: It will depend upon how complicated it is or how easy it might be to lock down some of the moving pieces on the economics—the expenses, the distributions and contributions. I guess the shorter you can squeeze the time period, the less room for those things to move is, but at the same time, typically, these have not been structured where people are willing to take the risk that their estimates were off.
Marc Migliazzo: That makes sense. And I guess there are other considerations at play as well, besides the way that investors in this space typically approach how the pricing formulas work. There’s also, of course, longstanding guidance that’s been put out by ILPA, most recently updated in 2023, that similarly recommends that LPs be given, at a minimum, 30 calendar days or 20 business days to make their election. So, those standards, of course, by ILPA are independent of the SEC’s rulemaking and are, in large part, driven by the complexity of these sorts of investment decisions that LPs are having to face. Not only do they need to review the election notice—they need to analyze the tax consequences for themselves, they need to digest the new fund terms for the continuation vehicle and the transaction terms under the purchase agreement or other transactional agreement, and then, of course, navigate all their own internal approval processes, which, oftentimes, include needing to go back to an investment committee to reevaluate the new economic terms, the go-forward thesis for the business, and their own other capital priorities for the institution. So, I can’t imagine that there are many LPs that would be happy to see a much shorter period.
Craig Marcus: I think you’re right. We definitely hear from a lot of LPs that they struggle with the speed of some of these transactions even when it was on the 20-business day timeline, completely independent from the tender offer rules and the interpretations under this exemptive order, it’s just a market question about what the market will bear in terms of structure and timing. Running a transaction process that’s too fast for some LPs to be able to get their work done can have the effect of effectively forcing LPs to sell because they can’t get through their institutional requirements around investment committee approvals and the like to be able to make a rollover election. And a 10-business day period is just going to exacerbate that for certain types of investors—pension funds, endowments, other institutional investors—who typically have robust internal procedures that are necessary to underwrite an investment or a rollover continuation of an investment. We can definitely expect to see some LPs resist accelerating the timeline on these, even if a sponsor is able to structure in a way that could satisfy the requirements under this exemptive order.
Marc Migliazzo: That makes sense. There’s also, of course, other things going on during the election period—it’s not just the existing LPs who are digesting the documents. Quite oftentimes, GP-led transactions have a syndication process that runs in parallel with that, where, although they reach final terms with the lead investor, there are still new money investors who are coming into the deal that are similarly looking to understand the terms of the LPA, the fund agreement, and the other transactional terms—analyze those—pulling together subscription materials, AML materials, negotiating side letters, all that. And all that has to occur in that same period of time. And so, if you shorten it too much, that adds undue pressure on that part of the transaction. Not to mention that rolling LPs, once they’ve gotten through their decision, and if they do decide to roll, are themselves likely, in many cases, to need to renew a side letter and need to negotiate that as well. So, there’s probably quite a lot to fit into a 10-business day period.
Craig Marcus: That’s definitely right. Now, obviously, you can try to organize the timeline of your transaction to maybe frontload some of those things before you launch your official 10-business day tender. But really, if there’s lots of moving pieces, like you describe, it’s not clear that the 10-business day tender is going to get you a whole lot of value if your transaction can’t otherwise close on a quicker timeline. And I suspect that, given market practice, given the LP constraints, notwithstanding the potential benefits of this exemptive order in the context of these GP-led secondary transactions, I’m not expecting to see a sea change in approach out of the gates.
Marc Migliazzo: All right, thanks again for spending your time and sharing this insight with us. For our listeners, you can also subscribe and listen to other Ropes & Gray podcasts wherever you regularly listen to your podcasts, including on Apple and Spotify. Thanks for listening.


Stay Up To Date with Ropes & Gray
Ropes & Gray attorneys provide timely analysis on legal developments, court decisions and changes in legislation and regulations.
Stay in the loop with all things Ropes & Gray, and find out more about our people, culture, initiatives and everything that’s happening.
We regularly notify our clients and contacts of significant legal developments, news, webinars and teleconferences that affect their industries.